
Top Gold Producers of 2025: Newmont, Agnico Eagle, Barrick and Peers Ranked by Ounces and AISC
For information only, not financial or investment advice. Do your own research or consult a licensed advisor. Read our disclaimer.

Who were the top gold producers in 2025, and what did it cost them to mine an ounce? Annual reports are now out for the major listed miners. The table below takes each company's 2025 output and all-in sustaining cost (AISC) straight from its year-end results. Three of the six are Canadian-listed, and Agnico Eagle's two biggest mines are in Ontario and Quebec.
2025 output and costs, from company reports
| Company (listing) | 2025 production | 2025 AISC (US$/oz) | Source |
|---|---|---|---|
| Newmont (NYSE: NEM) | 5.9 Moz attributable gold (5.7 Moz from core portfolio) | $1,358 (by-product) | Newmont, Feb. 19, 2026 |
| Agnico Eagle (NYSE/TSX: AEM) | 3.45 Moz payable gold | $1,339 | Agnico Eagle, Feb. 12, 2026 |
| Barrick Mining (NYSE: B, TSX: ABX) | 3.26 Moz gold | $1,637 | Barrick, Feb. 5, 2026 |
| AngloGold Ashanti | 3.09 Moz gold (group) | $1,709 (group) | AngloGold Ashanti, Feb. 2026 |
| Gold Fields | 2.44 Moz attributable gold-equivalent | $1,645 | Gold Fields, Feb. 2026 |
| Kinross Gold (TSX: K, NYSE: KGC) | 2.01 Moz attributable gold-equivalent | $1,571 per Au eq. oz sold | Kinross, Feb. 18, 2026 |
A caution on the comparison: AISC is a non-GAAP measure, and the companies don't calculate it the same way. Newmont quotes a by-product figure (it also gives a co-product figure of $1,609). Kinross and Gold Fields count gold-equivalent ounces, and AngloGold Ashanti reports group and managed-operation numbers separately. Read the table as a rough ranking, not a precise league table. It covers only these six Western-listed companies. Large producers that report on a different basis, such as China's Zijin Mining, are left out because we could not check comparable figures.
What stood out in 2025
Newmont led the group on volume by a wide margin. It also produced 28 million ounces of silver and 135,000 tonnes of copper. Those by-products help explain why its by-product AISC sits well below its co-product figure (Newmont).
Agnico Eagle had the lowest AISC in the table and the biggest Canadian base. In 2025, its Quebec mines produced about 1.11 million payable ounces, its Ontario mines about 1.01 million and its Nunavut mines about 870,000. Canadian Malartic (about 643,000 oz) and Detour Lake (about 693,000 oz) were its two largest contributors (Agnico Eagle). Its total cash cost and AISC came in slightly above the top of guidance, mainly because of higher royalties (about $42 per ounce) tied to an average realized gold price of $3,453 per ounce (same source).
Barrick shrank. Production fell 17% from 2024, and AISC rose 10% to $1,637 (Barrick). It also sold non-core assets, including Hemlo and its Tongon interest, which brought in $2.6 billion. Excluding those two divested assets, 2025 production would have been 3.03 million ounces (same source).
AngloGold Ashanti and Gold Fields grew. AngloGold's group output rose 16% year on year. It said Sukari in Egypt contributed 500,000 ounces (AngloGold Ashanti). Gold Fields' attributable gold-equivalent output rose 18%, helped by Salares Norte in Chile reaching commercial production in the third quarter of 2025. The mine generated US$808 million of free cash flow for the year, the most of any Gold Fields operation (Gold Fields).
Kinross held at about 2 million ounces. Its realized gold price in the fourth quarter averaged $4,144 per ounce (Kinross).
2026 guidance
| Company | 2026 production guidance | Source |
|---|---|---|
| Newmont | ~5.3 Moz attributable; by-product AISC ~$1,680/oz | Newmont |
| Agnico Eagle | 3.3–3.5 Moz; AISC $1,400–$1,550/oz | Agnico Eagle |
| Barrick | 2.90–3.25 Moz | Barrick |
| AngloGold Ashanti | 2.80–3.17 Moz (group) | AngloGold Ashanti |
| Kinross | ~2.0 Moz Au eq. | Kinross |
These were the targets set in February 2026. Mid-year updates may have changed them, so check the latest quarterly release before relying on any one number.
What it means for investors
Three themes come through. First, costs rose with the gold price. Agnico Eagle, for example, said higher royalties, which rise with the gold price, pushed its AISC above guidance. A higher gold price doesn't all turn into margin. Second, growth is scarce. Newmont's 2026 guidance is below its 2025 output, and Agnico is guiding flat. That helps explain the portfolio reshaping in these reports, such as Barrick's asset sales. Third, Canada is a big part of the supply picture. Agnico's Detour Lake and Canadian Malartic each produced more in 2025 than AngloGold's Sukari. Many investors see that as a lower-jurisdictional-risk exposure than mines in less stable regions. That is a judgment call, though, and Canadian operations aren't automatically low-cost.
Production rank isn't the same as investment quality. Margins, balance sheets, reserve life and valuation all matter, and none of this is a recommendation to buy any stock.
Related: gold hub, Canadian mining news and company profiles.
How we checked this: AI-drafted from the sources linked above and checked against them by our AI editor.
How we produced this article
AI-drafted from cited sources and checked by an AI editor before publishing. See How we fact-check.Related stories
Gold vs Silver for Canadian Investors in 2026: CAD Prices, the Gold-Silver Ratio and 50-Year Returns
Gold vs silver for Canadian investors: September 2026 prices in CAD, the gold-silver ratio, 10-, 20- and 50-year returns, volatility and demand drivers.

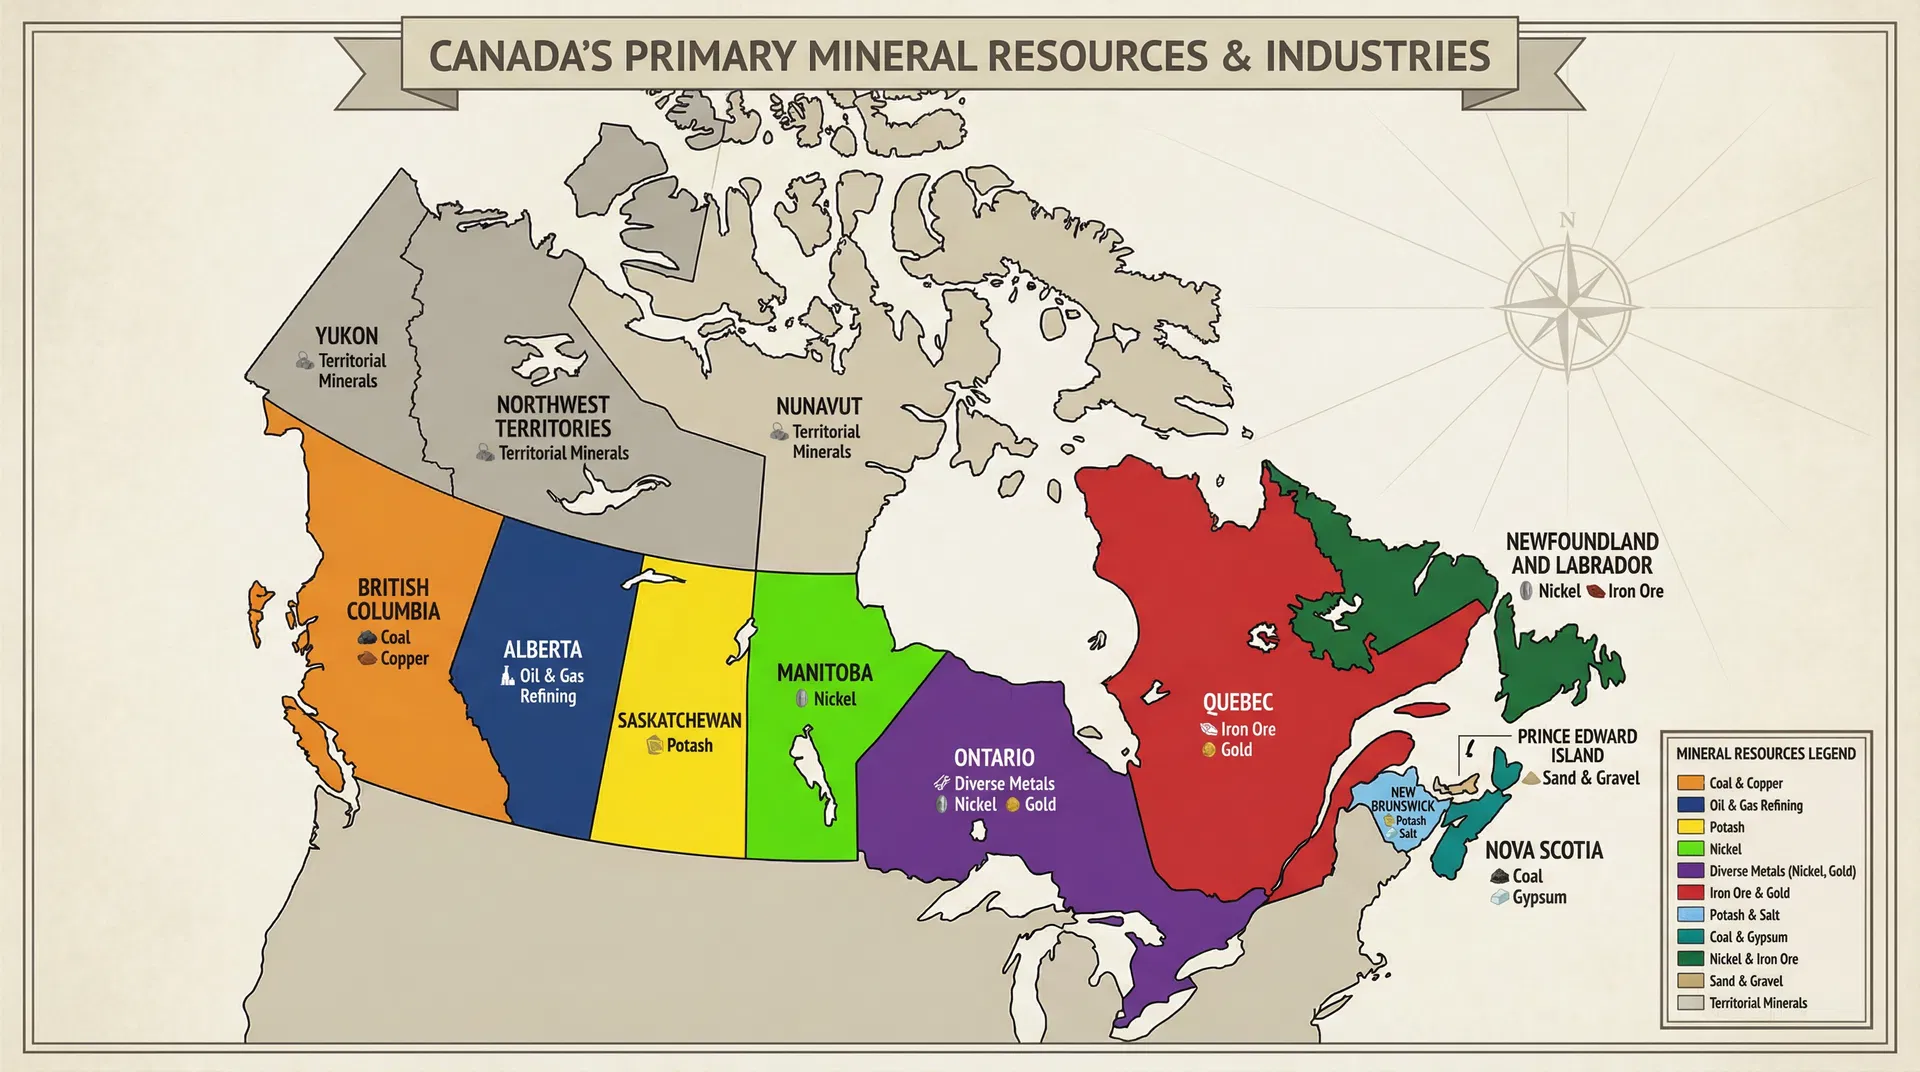
Canada's Provincial Mining Specialties: A Province-by-Province Breakdown of Key Minerals
Explore Canada's diverse mining landscape: from British Columbia's coal and copper to Quebec's iron ore and gold, and Saskatchewan's dominance in potash production.
Pacifica Silver Advances Claudia Project Amidst Robust Silver Market: An Exploration Update
Pacifica Silver has provided a crucial exploration update for its Claudia Silver-Gold Project, signaling continued development in a key region.
All content on Golden Shovel is for informational purposes only and is not financial, investment, or trading advice.